Hospital indemnity vs. accident insurance policies differ mainly in when they pay: hospital indemnity covers qualifying hospital stays, while accident insurance pays for specified injuries and treatment after covered accidents. Both are supplemental insurance plans that work alongside comprehensive health insurance, but they address different financial risks.
For employers and human resources (HR) teams, understanding these differences makes it easier to compare coverage and explain employee benefit options. This guide covers how each policy works, when benefits may overlap, common limitations, and what businesses should consider before offering either plan.
Key Takeaways
- Hospital indemnity insurance generally pays fixed benefits for qualifying hospital admissions or stays caused by covered illnesses or injuries.
- Accident insurance provides benefits for eligible accidental injuries and treatments, often without requiring hospitalization.
- Both policies may pay for the same accident when their separate coverage conditions are satisfied.
- Employers should compare premiums, exclusions, benefit schedules, hospital admission rules, and claim requirements before offering coverage.
- Neither policy replaces comprehensive medical insurance. Their value depends on employees’ existing coverage and financial needs.
What Is the Main Difference Between Hospital Indemnity and Accident Insurance?
The main difference between hospital indemnity and accident insurance is what triggers payment. Hospital indemnity insurance pays a fixed benefit for qualifying hospital events, while accident insurance provides benefits for covered accidental injuries and related treatment. Hospital indemnity insurance may pay when someone is admitted to a hospital for an illness, injury, or another qualifying condition.
Accident insurance can provide benefits for injuries such as fractures or dislocations, even when hospitalization is unnecessary. Both policies help address certain expenses that comprehensive health insurance may leave to the insured person, including deductibles, coinsurance, or household costs following a medical event. Here is how they compare:
| Feature | Hospital Indemnity Insurance | Accident Insurance |
| Main coverage | Qualifying hospital stays | Covered accidental injuries |
| Illness coverage | May cover illness-related hospitalization | Generally excludes unrelated illnesses |
| Emergency room visits | Covered only when included in the policy | May cover qualifying accident treatment |
| Benefit payments | Fixed amounts based on covered hospital events | Fixed benefits or eligible expense reimbursement |
| Hospital admission | Commonly required for primary benefits | Usually not required |
| Primary purpose | Financial support during hospitalization | Financial support following accidental injuries |
Neither policy replaces comprehensive medical coverage. Employees should review the benefit schedules and exclusions before deciding which type addresses their needs.
How Does Hospital Indemnity Insurance Work?
Hospital indemnity insurance provides a predetermined cash benefit when an eligible hospital event meets the policy’s requirements. Depending on the coverage, an employee may receive a payment for hospital admission, covered confinement days, or intensive care. Unlike comprehensive medical insurance, these payments are generally based on the covered event rather than the actual hospital bill. For example, an employee hospitalized for a qualifying illness may receive benefits even though no accident occurred.
The insurer reviews the claim and determines the payment according to the policy’s benefit schedule. Some policies limit covered hospital days, exclude certain conditions, or include waiting periods. Coverage for observation stays, outpatient procedures, and maternity care should be confirmed individually. For example, a business owner consulting an insurance agency in Conway, SC could request a sample benefit calculation showing how admission and daily confinement payments work together. This can help clarify whether both benefits apply to the same hospital stay and what payment limits the policy sets. Employers can review Benni Agency’s hospital indemnity insurance guide for more details about covered events and benefit calculations.
How Does Accident Insurance Work?
Accident insurance pays benefits when an employee experiences an injury covered by the policy. Common examples include fractures, burns, dislocations, and injuries requiring emergency medical treatment. Depending on the plan, benefits may apply to ambulance transportation, diagnostic imaging, surgery, rehabilitation, or follow-up appointments. Hospital admission is not always necessary. Some policies provide fixed payments for specific injuries or treatments.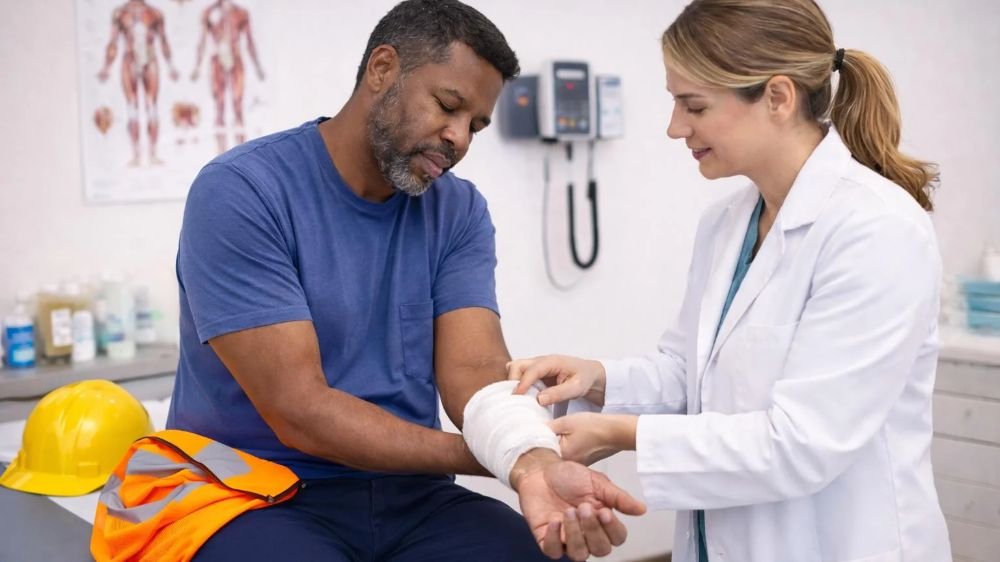
Others reimburse eligible accident-related expenses up to stated limits. Employees generally need to submit claim documentation, including treatment records and details about the accident. Accident insurance does not generally cover illnesses unrelated to an accident. Certain activities, injuries, or treatments may also be excluded. For a closer explanation of payment structures and covered treatments, see Benni Agency’s supplemental accident benefits guide.
When Would Hospital Indemnity or Accident Insurance Pay Benefits?
Hospital indemnity and accident insurance can respond differently to the same medical situation. The following examples show when each policy might provide coverage.
Scenario 1: An employee breaks a wrist.
An employee falls, breaks a wrist, receives emergency treatment, and returns home. Accident insurance may pay for the injury and covered treatment. Hospital indemnity insurance requiring inpatient admission generally would not pay.
Scenario 2: An employee is hospitalized for pneumonia.
An employee is admitted to a hospital for pneumonia. Hospital indemnity insurance may provide benefits for the qualifying stay. Accident insurance generally would not cover an illness unrelated to an accident.
Scenario 3: An employee is hospitalized after a serious fall.
Both policies may pay separate benefits. Accident insurance could cover eligible injuries and treatments, while hospital indemnity could pay for the qualifying hospital stay.
These examples are illustrative. Actual payments depend on each policy’s coverage definitions, exclusions, limits, and claim requirements.
What Should Conway, SC Employers Know About Hospital Indemnity and Accident Insurance?
Conway employers considering supplemental insurance should start by comparing the available benefits with their existing group health plans. Hospital indemnity and accident coverage respond to different events, so employees need to understand both the cost of coverage and the circumstances that would lead to a payment. A useful comparison considers deductibles, household expenses, and how benefit schedules match potential medical events.
The South Carolina Department of Insurance identifies hospital confinement indemnity and accident-only coverage as separate insurance categories. Employers can also use the department’s insurance company lookup to verify whether insurers are authorized to operate in South Carolina. Reviewing admission definitions, dependent eligibility, waiting periods, and exclusions can help clarify the differences between available policies. During enrollment, employers should explain employee contributions, coverage limitations, and claim procedures.
What Should Employers Compare Before Choosing Either Policy?
Employers should compare coverage details, employee costs, and benefit limitations before selecting hospital indemnity or accident insurance. The following questions can help guide that review:
- Coverage triggers: What injuries, hospital events, and treatments qualify for payment?
- Benefit amounts: Are payments fixed, calculated by covered days, or based on eligible expenses?
- Exclusions: Are waiting periods, pre-existing condition restrictions, or annual limits involved?
- Eligibility: Can employees cover spouses and dependents?
- Claims: What records and filing deadlines apply?
Hospital admission definitions deserve special attention. According to Medicare’s inpatient and outpatient guidance, observation care may remain outpatient treatment even when someone spends the night in a hospital. Supplemental policies determine eligibility under their own terms. Employers with Health Savings Account (HSA) arrangements should also consult Internal Revenue Service guidance when evaluating compatible supplemental coverage.
Should Employers Offer Hospital Indemnity Insurance, Accident Insurance, or Both?
Employers may offer hospital indemnity insurance, accident insurance, or both, depending on employee needs, existing coverage, and available budgets. Hospital indemnity insurance may appeal to employees concerned about expenses during a qualifying hospital stay. Accident insurance may interest employees who want protection against covered injuries that do not require hospitalization. Offering both can address different financial risks, but employees should understand the separate premiums and claim requirements.
Employers can review workforce needs, compare available benefits, and ask employees which coverage options they value. A broader employee benefits program may include voluntary insurance alongside comprehensive medical coverage. Benni Agency’s voluntary supplemental health benefits include options employers can evaluate when reviewing their benefits packages.