Home care business insurance usually includes general liability, professional liability, workers’ compensation, and vehicle coverage, depending on the services provided. Agencies may also need property, cyber, and employee dishonesty coverage to address risks that basic policies leave out.
For business owners and employers, the right policies depend on whether caregivers provide daily living assistance or skilled medical treatment. State licensing rules, staff responsibilities, transportation, and client contracts also affect the coverage needed. Understanding these differences helps agencies protect clients, employees, and business finances without paying for protection that does not match their work.
Key Takeaways
- Core insurance coverage: Home care businesses commonly need general liability, professional liability, workers’ compensation, and vehicle insurance based on their operations.
- Different care services: Nonmedical home care and skilled home health services create different liability risks and may require different insurance policies.
- South Carolina requirements: Licensed in-home care providers must meet state insurance or surety bond requirements, including specified minimum coverage amounts.
- Insurance costs: Premiums depend on caregiver duties, payroll, services offered, transportation, coverage limits, and claims history.
- Coverage gap prevention: Reviewing exclusions, contractor arrangements, vehicle use, and changing services helps identify risks that existing policies may not cover.
What Types of Insurance Does a Home Care Business Need?
Most home care agencies need several insurance policies because one policy rarely covers injuries, care-related mistakes, employee accidents, and driving risks together. The main types are:
- General liability insurance: May cover third-party bodily injury or property damage, such as a caregiver accidentally damaging a client’s furniture. It may not cover harm caused by professional care services.
- Professional liability insurance: May cover claims that negligent care, missed duties, or professional errors caused a client harm. Medical services may require coverage specifically written for clinical care.
- Workers’ compensation insurance: Pays statutory benefits for qualifying employee injuries, such as a caregiver hurt while transferring a client. South Carolina generally requires it for employers regularly employing four or more workers, subject to exemptions. Employers can review how workers’ compensation insurance works.
- Commercial auto insurance: Covers qualifying accidents involving agency-owned vehicles. If caregivers drive personal cars for work, the agency should also ask about hired and non-owned auto liability coverage.
Crime or employee dishonesty coverage: May provide protection against covered theft of client money or personal belongings by employees, depending on the policy’s limits and exclusions. Home care agencies should make sure their insurance covers caregivers working at different client locations. For businesses operating across Charleston, consulting an insurance broker Charleston, SC businesses can work with may help clarify coverage limits, employee-related risks, and insurance needs for travel between visits.
Do Nonmedical Home Care and Home Health Agencies Need Different Insurance?
Yes. Nonmedical home care agencies and home health agencies often need different insurance because their services create different liability risks. Nonmedical home care generally helps clients with bathing, dressing, meal preparation, mobility, companionship, and other daily activities. Insurance must address client injuries, accidental property damage, alleged neglect, employee injuries, and transportation when offered. Professional liability wording matters even when workers do not deliver medical treatment. Home health agencies provide skilled services such as nursing or physical therapy.
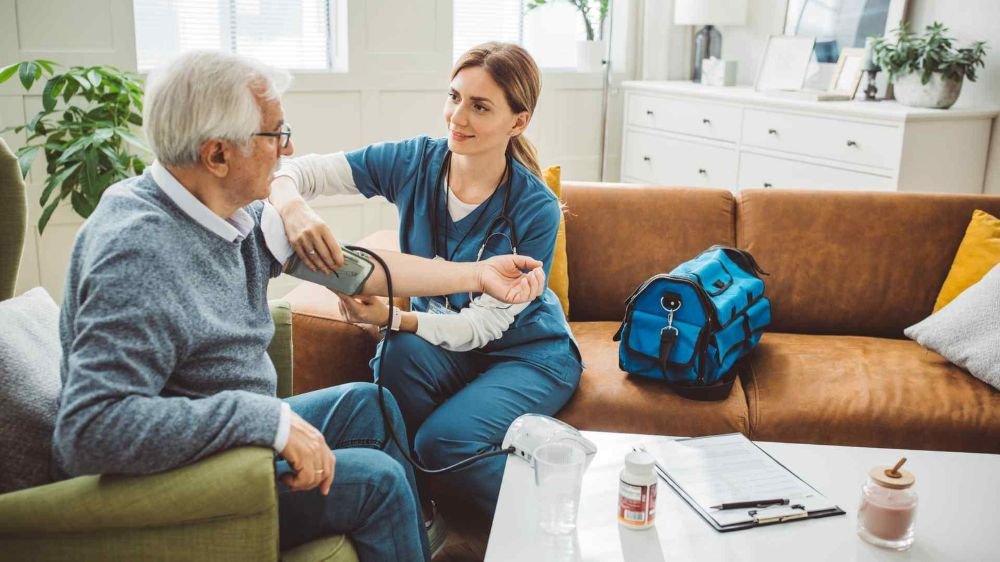
Their policies must account for potential clinical errors, treatment-related injuries, documentation mistakes, and the professional roles of licensed staff. General liability insurance alone usually does not address these risks. South Carolina also licenses the two types of providers under separate laws. In-home care is governed by Chapter 70 of Title 44, while home health agencies fall under Chapter 69. The state’s licensing category should match the agency’s actual services. An agency offering both types of care should disclose all services and confirm that each is insured under the appropriate policy. Through its commercial insurance services, Benni Agency helps employers examine liability risks, employee injuries, and vehicle use. Discuss your agency’s insurance needs and identify coverage questions worth addressing before purchasing or renewing a policy.
What Additional Insurance Should a Home Care Agency Consider?
Home care agencies may need more coverage when they handle private client information, operate an office, or offer transportation. Cyber liability insurance may address certain data breaches, privacy incidents, response expenses, and claims arising from covered cyber events. Commercial property insurance may cover office equipment, computers, and furniture damaged by insured events. Business income coverage may help with qualifying lost income after covered property damage interrupts operations.
A Business Owner’s Policy (BOP) can package some property and general liability protection, but eligibility varies and care-related professional claims may still require separate insurance. Agencies that manage client money or regularly transport clients should also review employee theft and commercial auto insurance coverage. Choose additions based on actual services and policy exclusions.
What Insurance and Licensing Rules Apply to Home Care Businesses in Charleston, SC?
Home care businesses operating in Charleston, South Carolina, must consider state healthcare licensing, insurance requirements, and any applicable city business license. The South Carolina Department of Public Health licenses nonmedical in-home care providers under Regulation 60-122. Under the 2026 requirements, applicants must show liability insurance or a surety bond with at least $100,000 per occurrence and $300,000 in aggregate, plus indemnity coverage for client losses. Workers’ compensation coverage is required when applicable under state law. These minimums apply to licensed in-home care providers, not automatically to every home health agency.
Home health agencies need separate state licensure under Title 44, Chapter 69. Businesses that operate or generate income inside Charleston city limits must also obtain a city business license. The state requires appropriate zoning documentation for an in-home care provider’s primary office. Before opening or expanding, confirm the correct healthcare license, check municipal requirements, and verify that insurance documents reflect the services and locations actually operated.
Benni Agency helps Charleston home care businesses review insurance coverage, licensing requirements, and employee risks. Through its insurance broker services, businesses can assess policy limits, exclusions, and coverage needs before expanding operations.
How Much Does Home Care Business Insurance Cost?
Home care business insurance has no single fixed price. Premiums depend on the services an agency provides, number of caregivers, payroll, revenue, claims history, vehicle use, coverage limits, and deductibles. A nonmedical agency with limited transportation may have a different insurance budget from a home health agency providing skilled nursing.
Employers with more caregivers may also spend more on workers’ compensation because payroll and job classifications affect pricing. Compare quotes using the same coverage types, limits, deductibles, and exclusions. Ask whether professional liability includes the activities your caregivers perform and whether driving and client property exposures are addressed. A lower premium is not useful if it leaves a major risk uninsured.
How Can Home Care Business Owners Avoid Insurance Coverage Gaps?
Home care business owners can reduce coverage gaps by reviewing what caregivers actually do, rather than relying on policy names alone. Check that professional liability covers the services performed, including personal care or skilled treatment when applicable. Confirm whether independent contractors, temporary staff, and referred caregivers are included. Review agency-owned vehicles and employees’ personal vehicles used for client trips.
Look closely at exclusions for abuse allegations, theft, medication assistance, privacy events, and care outside stated service areas. Coverage for these situations varies. Keep written service descriptions current, document changes in staffing or transportation, and revisit insurance at renewal or whenever operations change. Agencies should also understand how much liability insurance their activities may require.
One thought on “What Insurance Does a Home Care Business Need?”
Comments are closed.