Workers’ compensation insurance helps pay benefits when an employee suffers a qualifying work-related injury or illness. It can cover medical treatment, part of lost wages, and other benefits required by state law.
For employers, understanding this coverage matters because it addresses workplace injury costs and is legally required for many businesses. Rules differ by state, and coverage does not apply to every injury. Knowing what is included, who needs a policy, and how claims are handled helps business owners and human resources teams plan for workplace incidents and meet their responsibilities.
Key Takeaways
- Workers’ compensation insurance provides benefits for qualifying work-related injuries and illnesses while limiting certain employer liabilities.
- Coverage may include medical treatment, partial lost wages, disability benefits, rehabilitation, and death benefits for eligible dependents.
- South Carolina generally requires businesses with four or more regularly employed workers to maintain coverage, subject to statutory exemptions.
- Prompt injury reporting and accurate documentation are important parts of the workers’ compensation claims process.
- Insurance premiums depend on factors such as payroll, employee duties, occupational risks, and claims history.
What Is Workers’ Compensation Insurance?
Workers’ compensation insurance is employer-funded coverage for employees who are injured or become ill because of their work. It provides benefits under state workers’ compensation laws without generally requiring an injured employee to pursue a lawsuit to obtain those benefits.
For example, if a warehouse employee strains their back while lifting a package, workers’ compensation may pay for authorized medical treatment and part of the wages lost during recovery. An illness caused by qualifying workplace exposure may also be covered. Whether a particular condition qualifies depends on the circumstances and applicable state law.
Most workers’ compensation systems follow a no-fault approach. This means an eligible employee generally does not need to prove the employer caused the injury through negligence. In exchange for defined benefits, employers generally receive protection against certain workplace injury lawsuits, although exceptions can apply.
Employers typically pay the insurance premiums. Workers’ compensation addresses qualifying employee injuries and illnesses, while general liability insurance generally covers certain claims involving people outside the workforce, such as customers or visitors.
What Does Workers’ Compensation Insurance Cover?
Workers’ compensation insurance generally covers medical care, partial wage replacement, and other benefits for qualifying workplace injuries or illnesses. The benefits available depend on the injury and applicable state law.
For example, a business owner working with an insurance agency in Hilton Head Island, SC may need to review South Carolina’s workers’ compensation rules alongside those of other states where employees work. The same consideration applies to employers nationwide, since coverage requirements and benefits can differ from state to state.
Coverage may apply to an employee injured in a workplace fall, a warehouse worker hurt while lifting equipment, or an employee who develops an illness linked to occupational exposure. Injuries can also occur while employees perform assigned duties outside their usual workplace. Coverage depends on the connection to employment rather than the location alone. Benefits generally fall into two main categories: medical and wage-related benefits, and support for disability or work-related death.
Medical Treatment and Lost Wages
Covered medical care may include emergency treatment, doctor visits, prescribed medication, surgery, and physical therapy. Employees unable to work during recovery may receive partial wage replacement rather than their full paycheck. In South Carolina, employers generally select the authorized treating doctor. Employees should confirm follow-up treatment arrangements after receiving any necessary emergency care.
Disability, Rehabilitation, and Death Benefits
Disability benefits may apply when a workplace injury temporarily or permanently limits an employee’s ability to work. Some claims also involve rehabilitation services or assistance returning to suitable duties. If a covered work-related injury causes death, eligible dependents may receive financial benefits, and certain funeral expenses may be covered. Eligibility and payment amounts depend on state law.
What Does Workers’ Compensation Insurance Not Cover?
Workers’ compensation insurance does not cover every injury an employee experiences. The injury generally must arise from employment and satisfy applicable state requirements. Injuries unrelated to job duties typically fall outside coverage. For example, an employee injured while completing a personal errand may not qualify simply because the incident occurred during working hours. Ordinary commuting injuries are also generally excluded, although certain work-related travel situations may qualify.
State laws may exclude injuries intentionally caused by employees or injuries resulting from intoxication under specified circumstances. Workers’ compensation also generally does not compensate employees for pain and suffering. Its benefits follow statutory rules rather than ordinary personal injury damages. Coverage decisions depend on the circumstances of each claim and applicable state law.
Who Needs Workers’ Compensation Insurance?
Whether an employer needs workers’ compensation insurance depends on state law, workforce size, and the nature of its operations. Many states require qualifying employers to maintain coverage, although requirements and exemptions differ. Employers should review the rules in every state where their employees work. An organization may have obligations in one state that differ from those in another.
Industry-specific exemptions and rules affecting business owners, independent contractors, and subcontractors may also influence coverage requirements. Operating without legally required insurance can expose businesses to penalties and financial responsibility for workplace injuries. Employers should review their coverage obligations when hiring employees, opening new locations, or changing business operations.
Workers’ Compensation Requirements in South Carolina
As of 2026, the South Carolina Workers’ Compensation Commission generally requires businesses regularly employing four or more employees to maintain coverage. Part-time workers and family members count toward this threshold. Exemptions include certain employment categories and businesses with annual payroll below $3,000. Employers should review the Commission’s official employer guidance before assuming an exemption applies.
Employees, Independent Contractors, and Business Owners
Independent contractors are treated differently from employees, but payment methods alone do not establish worker status. In South Carolina, paying someone through Form 1099 does not automatically remove workers’ compensation obligations. Business owners may also have different coverage options. General contractors should review their potential responsibility for subcontractors and workers who lack coverage.
How Does Workers’ Compensation Insurance Work?
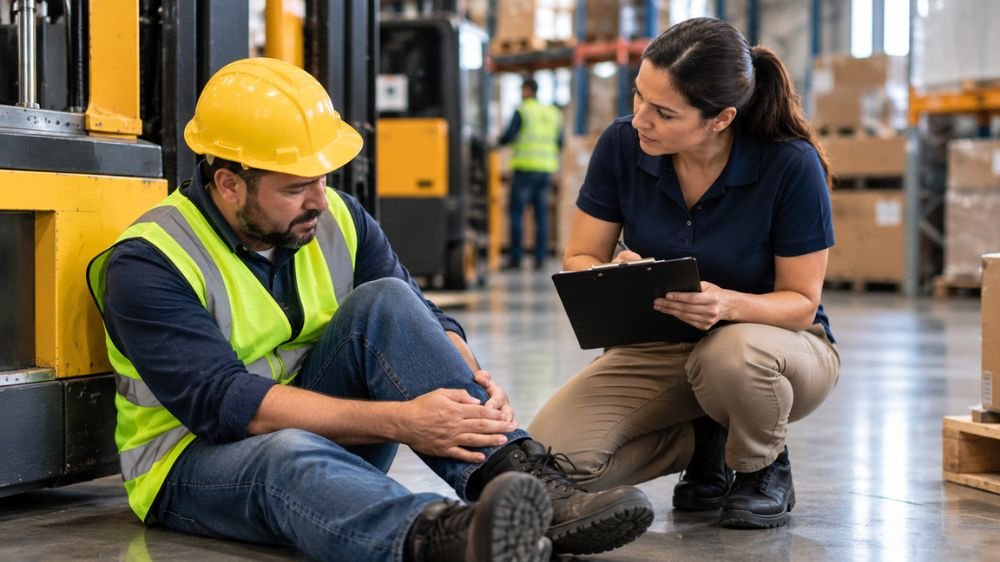
Workers’ compensation insurance works through a claims process that begins when an employee reports a qualifying work-related injury or illness. The employer documents the incident, and the insurer or claims administrator evaluates eligibility.
The process generally involves five steps:
- Report the injury: The employee informs a supervisor and receives necessary medical attention.
- Document the incident: The employer records relevant details and reports the claim as required.
- Review the claim: The insurer or claims administrator evaluates the injury and supporting information.
- Provide approved benefits: Eligible employees receive qualifying medical or wage-related benefits.
- Resolve disputes: Employees may challenge denied or disputed claims through applicable state procedures.
South Carolina’s injured worker guidance recommends immediate reporting. Failing to report an injury within 90 days may affect benefit eligibility.
How Much Does Workers’ Compensation Insurance Cost?
Workers’ compensation insurance costs depend on payroll, employee job duties, claims history, and applicable state insurance rules. Businesses with similar employee counts may pay different premiums because their workplace risks differ. Insurers commonly use classification codes to categorize work based on occupational risks. Premium calculations often involve rates per $100 of covered payroll.
Eligible employers may also receive an experience modification factor, which adjusts premiums based on previous claims compared with expected losses for similar operations. For example, employees performing office duties generally have different occupational risks from employees working with heavy machinery. Insurers may initially calculate premiums using estimated payroll and later adjust them through a payroll audit. Accurate employee classifications and payroll records help support appropriate premium calculations.
How Can a Business Get Workers’ Compensation Insurance?
Businesses can obtain workers’ compensation insurance by identifying their coverage requirements and providing accurate information about their operations to an authorized insurer or insurance broker. Employers should prepare annual payroll estimates, employee job descriptions, business locations, and previous claims information before requesting coverage.
They should also review subcontractor arrangements, policy terms, employee classifications, reporting requirements, and effective dates. In South Carolina, employers can obtain coverage through licensed insurance carriers. Other arrangements, including an assigned-risk program and approved self-insurance options, may be available under applicable requirements. Benni Agency provides workers’ compensation as part of its commercial insurance services, allowing employers to review this coverage alongside other business insurance needs.
One thought on “Workers’ Compensation Insurance Basics”
Comments are closed.